
06 Oct RBI Extends Directions for Baghat Urban Co-op Bank: Key for UPSC
✎ The RBI’s powers under Sections 35A and 56 of the Banking Regulation Act, 1949, enable it to issue binding directions to urban co-operative banks to address financial weaknesses or governance issues, ensuring depositor protection…
Subject Relevance — Where This Topic Fits
- GS Paper III — Indian Economy and Issues Relating to Planning, Mobilisation of Resources, Growth, Development and Employment | GS Paper III — Role of Financial Institutions and Regulatory Bodies
- Prelims: Banking Regulation Act, 1949, Section 35A, Urban Co-operative Banks, RBI Directions, Financial Stability, Banking Sector Regulation, Public Interest Clause, Section 56 of Banking Regulation Act
- Essay: Role of regulatory institutions in safeguarding financial stability, Balancing public interest and financial sector governance
Quick Revision: The RBI’s powers under Sections 35A and 56 of the Banking Regulation Act, 1949, enable it to issue binding directions to urban co-operative banks to address financial weaknesses or governance issues, ensuring depositor protection and systemic stability.
Why is this in the news?
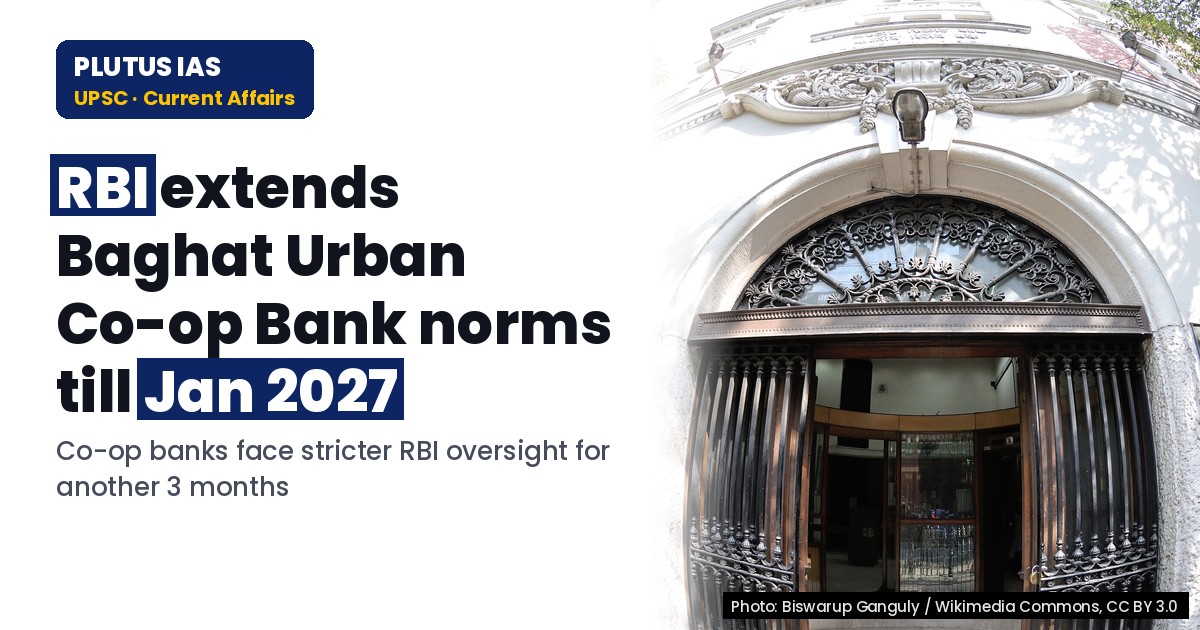
The Reserve Bank of India (RBI) has extended regulatory directions to The Baghat Urban Co-operative Bank Limited, Solan, under Sections 35A and 56 of the Banking Regulation Act, 1949, for a further period of three months, from October 8, 2026, to January 8, 2027. This extension, issued in the exercise of statutory powers, underscores the RBI’s ongoing supervisory role in addressing governance and financial stability concerns in urban co-operative banks, a critical segment of India’s banking ecosystem.
Background
- Urban Co-operative Banks (UCBs) are a distinct category of banks in India, primarily serving urban and semi-urban areas, and are governed by the provisions of the Banking Regulation Act, 1949, and the Co-operative Societies Act of the respective states.
- The RBI, as the central banking regulator, exercises supervisory and regulatory powers over UCBs to ensure financial stability, depositor protection, and adherence to prudential norms.
- Section 35A of the Banking Regulation Act, 1949, empowers the RBI to issue directions to banking companies, including co-operative banks, in the public interest or to prevent banking policy violations.
- Section 56 of the Act extends these powers to co-operative banks, enabling the RBI to issue specific directions for their regulation and supervision.
- The RBI’s regulatory directions often include restrictions on lending, deposit acceptance, dividend distribution, and other operational activities to address financial weaknesses or governance issues.
- UCBs have faced challenges such as weak governance, financial mismanagement, and liquidity constraints, necessitating frequent regulatory interventions by the RBI.
What are the Regulatory Powers of the RBI under Sections 35A and 56 of the Banking Regulation Act, 1949?
- Section 35A of the Banking Regulation Act, 1949, empowers the RBI to issue directions to banking companies, including co-operative banks, in the public interest or to prevent contravention of banking laws and policies.
- The RBI may issue directions on matters such as capital adequacy, asset classification, income recognition, provisioning, and exposure norms to ensure financial stability and depositor protection.
- Section 56 extends these powers specifically to co-operative banks, enabling the RBI to issue directions tailored to their unique operational and governance structures.
- The RBI’s directions may include restrictions on the acceptance of fresh deposits, payment of dividends, granting of loans and advances, and other operational activities to address financial weaknesses or governance lapses.
- The RBI’s powers under these sections are exercised in the broader public interest, ensuring systemic stability and protecting the interests of depositors and creditors.
- The directions issued under these sections are not indicative of the RBI’s satisfaction with the financial position of the bank but are precautionary measures to prevent systemic risks.
- The RBI’s supervisory role over UCBs is part of its broader mandate to maintain financial stability and ensure compliance with prudential norms across the banking sector.
Key Features
| Feature | Significance |
|---|---|
| Section 35A of the Banking Regulation Act, 1949 | Empowers the Reserve Bank of India (RBI) to issue directions to banking companies, including co-operative banks, to regulate their affairs in the public interest or to prevent affairs detrimental to depositors. |
| Section 56 of the Banking Regulation Act, 1949 | Extends the applicability of Section 35A to co-operative societies engaged in banking, ensuring regulatory oversight over urban co-operative banks. |
| Directive under Section 35A read with Section 56 | A legally binding order issued by the RBI to The Baghat Urban Co-operative Bank Limited, Solan, to enforce specific operational or financial restrictions for a defined period. |
| Extension of Directive Period | The RBI’s decision to prolong the duration of the Directive beyond the initially stipulated period, subject to periodic review, to address unresolved concerns. |
| Public Interest Criterion (Section 35A) | The RBI’s justification for extending the Directive, emphasizing the necessity to protect depositors and maintain systemic stability in the banking sector. |
Why it Matters
Regulatory Oversight and Financial Stability
- Demonstrates the RBI’s proactive role in supervising co-operative banks to prevent financial distress, which could otherwise lead to systemic risks in the banking ecosystem.
- Highlights the importance of timely regulatory intervention to safeguard depositor interests, particularly in institutions with limited deposit insurance coverage.
- Reinforces the RBI’s mandate under the Banking Regulation Act to maintain public confidence in the banking system through enforceable directives.
Governance in Urban Co-operative Banks (UCBs)
- Illustrates the challenges in regulating UCBs, which operate under a distinct legal framework compared to commercial banks, necessitating specialized oversight mechanisms.
- Underscores the need for robust internal governance and compliance frameworks within UCBs to avoid regulatory penalties and operational disruptions.
- Serves as a case study for the RBI’s evolving approach to balancing regulatory strictness with the operational realities of co-operative banking institutions.
Legal and Institutional Framework
- Reinforces the legal authority of the RBI to issue binding directives under Sections 35A and 56, ensuring accountability in the banking sector.
- Demonstrates the interplay between statutory provisions and regulatory discretion in addressing financial irregularities or governance failures.
- Provides a precedent for future regulatory actions against other co-operative banks facing similar challenges, ensuring consistency in enforcement.
Depositor Protection
- Emphasizes the RBI’s commitment to protecting depositors, especially in institutions where the risk of financial distress is higher due to limited capital buffers.
- Highlights the limitations of deposit insurance in co-operative banks, making regulatory oversight critical to prevent losses for small depositors.
- Serves as a reminder of the need for depositors to exercise due diligence while choosing banking partners, particularly in the co-operative sector.
Challenges
1. Regulatory Arbitrage in Co-operative Banks
- Co-operative banks often exploit gaps between regulatory frameworks applicable to commercial banks and those specific to co-operative institutions.
- Limited alignment with Basel III norms or other international banking standards, creating systemic vulnerabilities.
- Inconsistent application of governance norms across different types of co-operative banks, leading to regulatory challenges.
UPSC Link: Co-operative Societies Act, 1912
2. Financial Distress and Liquidity Risks
- Urban co-operative banks are prone to liquidity crises due to concentrated loan portfolios, poor asset-liability management, or fraudulent activities.
- Limited access to emergency liquidity assistance (ELA) compared to scheduled commercial banks, exacerbating financial distress.
- High dependence on short-term deposits makes UCBs vulnerable to sudden withdrawal pressures during periods of economic stress.
UPSC Link: Liquidity Coverage Ratio (LCR)
3. Governance Failures and Fraud Risks
- Weak internal controls, lack of independent oversight, and inadequate audit mechanisms in co-operative banks increase the risk of fraud and mismanagement.
- Over-reliance on politically connected leadership or local patronage networks can compromise professional governance standards.
- Delayed detection of financial irregularities due to inadequate reporting systems or collusion among stakeholders.
UPSC Link: Corporate Governance in Banks
4. Deposit Insurance Limitations
- The Deposit Insurance and Credit Guarantee Corporation (DICGC) covers only up to ₹5 lakh per depositor per bank, leaving larger deposits exposed to risk.
- Small depositors in co-operative banks often lack awareness of insurance coverage limits, increasing their vulnerability to losses.
- The RBI’s directive in this case underscores the inadequacy of deposit insurance as a standalone safeguard for depositors.
UPSC Link: Deposit Insurance and Credit Guarantee Corporation (DICGC)
5. Operational Disruptions and Customer Impact
- Prolonged regulatory directives can lead to operational restrictions, such as limits on withdrawals or lending, affecting customer confidence and financial inclusion.
- Small businesses and individuals relying on UCBs for credit or savings may face temporary financial hardships due to regulatory actions.
- Reputational damage to the bank can result in long-term loss of business, even after compliance with directives.
UPSC Link: Financial Inclusion and Banking Outreach
Challenges — UPSC Perspective
| Issue | Concern |
|---|---|
| Regulatory Arbitrage | Exploitation of gaps between co-operative and commercial banking regulations, leading to inconsistent oversight. |
| Liquidity Crunch | Inability to meet withdrawal demands due to poor asset-liability management or sudden deposit outflows. |
| Governance Deficiencies | Weak internal controls, lack of transparency, and susceptibility to fraud or mismanagement. |
| Deposit Insurance Gaps | Inadequate coverage for large deposits, leaving small depositors and businesses exposed to risk. |
| Operational Restrictions | Regulatory directives limiting banking services, causing inconvenience to customers and disrupting financial flows. |
| Reputational Damage | Loss of public trust due to regulatory actions, impacting long-term sustainability of the bank. |
Way Forward
- Conduct a comprehensive audit of The Baghat Urban Co-operative Bank Limited to identify root causes of regulatory non-compliance and financial distress.
- Strengthen the RBI’s supervisory framework for co-operative banks by enhancing on-site inspections and off-site monitoring mechanisms.
- Mandate the adoption of Basel III norms or equivalent standards for urban co-operative banks to improve risk management and capital adequacy.
- Increase awareness among depositors about the limitations of deposit insurance and the importance of diversifying banking relationships.
- Introduce a graded regulatory approach for co-operative banks based on size, risk profile, and systemic importance to ensure proportional oversight.
- Enhance transparency in the issuance of RBI directives by publishing detailed justifications and timelines for compliance.
- Promote the consolidation of smaller co-operative banks into larger entities to improve governance, risk management, and operational efficiency.
- Develop a crisis management framework for co-operative banks to address liquidity crises and prevent systemic contagion.
UPSC Value Addition
Keywords for Mains Answer-Writing
Urban Co-operative Banks · Banking Regulation Act, 1949 · Reserve Bank of India (RBI) · Section 35A of Banking Regulation Act · Section 56 of Banking Regulation Act · Directions to banks · Financial Regulation and Supervision · Public Interest in Banking · Banking Sector Governance · Co-operative Banking Sector · RBI’s Regulatory Powers · Banking Sector Reforms · Financial Stability · Regulatory Arbitrage · Banking Sector Oversight
Concept Flow
RBI identifies financial irregularities or governance failures in The Baghat Urban Co-operative Bank Limited → RBI issues Directive under Section 35A read with Section 56 → Directive imposes operational restrictions (e.g., withdrawal limits) → Bank fails to address concerns within stipulated period → RBI extends Directive period to protect depositors and maintain stability → Public interest justification cited for extension → Ongoing review to assess compliance and risk mitigation → Potential resolution through restructuring, merger, or liquidation if necessary.
Prelims Practice Questions
Q1. Consider the following statements about the Reserve Bank of India’s (RBI) powers under the Banking Regulation Act, 1949:
1. Section 35A empowers the RBI to issue directions to banks in the public interest.
2. Section 56 of the Act confers powers on the RBI to regulate co-operative societies.
3. The RBI can issue directions to banks without any time-bound extension.
4. The RBI’s directions under these sections are binding on all scheduled commercial banks.
How many of the above statements are correct?
- Only one
- Only two
- Only three
- All four
Answer: Only three — Statements 1 and 2 are correct as they accurately reflect the provisions of Section 35A and Section 56 of the Banking Regulation Act, 1949. Statement 3 is incorrect because the RBI can extend the period of its directions under specific circumstances, as seen in the case of The Baghat Urban Co-operative Bank Limited. Statement 4 is incorrect as the RBI’s powers under these sections primarily apply to co-operative banks and certain other categories, not all scheduled commercial banks.
Q2. Which of the following is NOT a power vested in the Reserve Bank of India under the Banking Regulation Act, 1949?
- Issuing directions to banks in the interest of depositors
- Extending the period of its directions to banks
- Regulating the interest rates on loans and advances
- Supervising the functioning of co-operative banks
Answer: Regulating the interest rates on loans and advances — The RBI does not have the power to regulate interest rates on loans and advances under the Banking Regulation Act, 1949. This power lies with the central government or other regulatory bodies like the Monetary Policy Committee. The RBI can issue directions, extend periods, and supervise co-operative banks under the Act.
Q3. Assertion (A): The Reserve Bank of India can issue directions to co-operative banks under Section 35A of the Banking Regulation Act, 1949.
Reason (R): Section 56 of the Act empowers the RBI to regulate co-operative societies engaged in banking business.
In the context of the above statements, which of the following is correct?
- Both A and R are true, and R is the correct explanation of A
- Both A and R are true, but R is NOT the correct explanation of A
- A is true, but R is false
- A is false, but R is true
Answer: Both A and R are true, but R is NOT the correct explanation of A — Both Assertion (A) and Reason (R) are true. The RBI can issue directions to co-operative banks under Section 35A, and Section 56 empowers it to regulate co-operative societies engaged in banking. Reason (R) correctly explains Assertion (A) as the legal basis for the RBI’s regulatory powers over such entities.
Mains Practice Question
✍ Examine the constitutional and statutory framework governing the Reserve Bank of India’s (RBI) powers to issue directions to co-operative banks under Sections 35A and 56 of the Banking Regulation Act, 1949. Critically analyse the rationale behind such regulatory interventions and their implications for financial stability and depositor protection. (15 Marks)
Approach: MODEL-ANSWER SKELETON:
1. **Statutory Basis**:
– Section 35A of the Banking Regulation Act, 1949: Empowers the RBI to issue directions to banks in the interest of banking policy, depositors, or for the proper management of a bank. Cite the specific sub-sections and the scope of these powers.
– Section 56: Extends RBI’s regulatory authority to co-operative societies engaged in banking, including urban co-operative banks (UCBs). Highlight the distinction between co-operative banks and other commercial banks.
2. **Constitutional and Governance Context**:
– RBI’s role as the central bank under the Constitution of India (Entry 35, Union List, Seventh Schedule).
– The principle of ‘public interest’ as the overarching rationale for regulatory interventions (Article 39(b) of the Directive Principles of State Policy may be referenced conceptually).
– The RBI’s mandate to maintain financial stability and protect depositors (Preamble to the Banking Regulation Act).
3. **Rationale for Directions**:
– **Financial Stability**: Preventing bank failures, systemic risks, and contagion effects (e.g., cases like Punjab and Maharashtra Co-operative Bank Limited).
– **Depositor Protection**: Ensuring the safety of depositors’ funds, particularly in UCBs with weaker governance structures.
– **Proper Management**: Addressing issues like poor asset quality, inadequate capital, or mismanagement (as seen in the case of The Baghat Urban Co-operative Bank Limited).
4. **Implications and Challenges**:
– **Positive Implications**: Enhanced oversight, improved governance, and restoration of public confidence in UCBs.
– **Challenges**: Potential conflicts between RBI’s regulatory autonomy and the autonomy of co-operative institutions; delays in resolution due to prolonged extensions (e.g., the 3-month extension in the given case).
– **Comparative Perspective**: Contrast RBI’s powers with those of other regulators (e.g., SEBI, IRDAI) and discuss the need for harmonised regulatory frameworks.
5. **Recent Developments and Case Law**:
– Reference to RBI’s recent directions to UCBs (e.g., the case of The Baghat Urban Co-operative Bank Limited, Solan).
– Judicial precedents affirming RBI’s powers (e.g., judgments upholding RBI’s regulatory authority over co-operative banks).
6. **Conclusion**:
– Balancing regulatory oversight with the autonomy of co-operative institutions.
– The necessity of timely and effective interventions to maintain financial stability and depositor confidence.
Source: RBI
Himachal Pradesh PCS (HPPSC (HAS)) — State PCS Practice
Prelims: Under which sections of the Banking Regulation Act, 1949, was the period extended for The Baghat Urban Co-operative Bank Limited, Solan, as per recent directions?
- Sections 35A and 56
- Sections 34A and 55
- Sections 36A and 57
- Sections 33A and 54
Answer: Sections 35A and 56 — The extension was granted under Sections 35A read with Section 56 of the Banking Regulation Act, 1949.
Mains: Discuss the significance of the recent extension of period for The Baghat Urban Co-operative Bank Limited, Solan, under the Banking Regulation Act, 1949. Highlight its implications for the cooperative banking sector in Himachal Pradesh.
Generated by AanyaAi for educational purpose.
Related guides on our sites
- Best PSIR optional coaching for upsc
- Best PSIR optional teacher for upsc
- Best teacher of PSIR optional for upsc
- Best PSIR optional coaching in delhi for UPSC

- यूपीआई लेन-देन पर एमडीआर पर जीएसटी न लगाने की मांग: सी. रंगराजन - October 6, 2026
- RBI Extends Directions for Baghat Urban Co-op Bank: Key for UPSC - October 6, 2026
- तमिलनाडु सरकार ने ‘अन्नन सीर योजना’ के लिए 812 करोड़ रुपये आवंटित किए - October 6, 2026
No Comments