
08 Sep PM’s Speech at Global Fintech Fest 2026: Key Highlights for UPSC
✎ UPI, launched in 2016, has revolutionised India’s digital payments ecosystem and expanded to 11 countries, while India’s sovereign credit rating upgrade reflects its macroeconomic stability and structural reforms.
Subject Relevance — Where This Topic Fits
- GS Paper III — Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment | GS Paper III — Science and Technology — developments and their applications and effects in everyday life | GS Paper III — Awareness in the fields of IT, Space, Computers, robotics, nano-technology, bio-technology and issues relating to intellectual property rights
- Prelims: UPI, NPCI, Digital Payments, Sovereign Credit Rating, Macroeconomic Stability, Financial Inclusion, Fintech Innovation, G20 Digital Economy Working Group
- Essay: The role of technology in transforming governance and public service delivery, India’s emergence as a global leader in digital public infrastructure
Quick Revision: UPI, launched in 2016, has revolutionised India’s digital payments ecosystem and expanded to 11 countries, while India’s sovereign credit rating upgrade reflects its macroeconomic stability and structural reforms.
Why is this in the news?
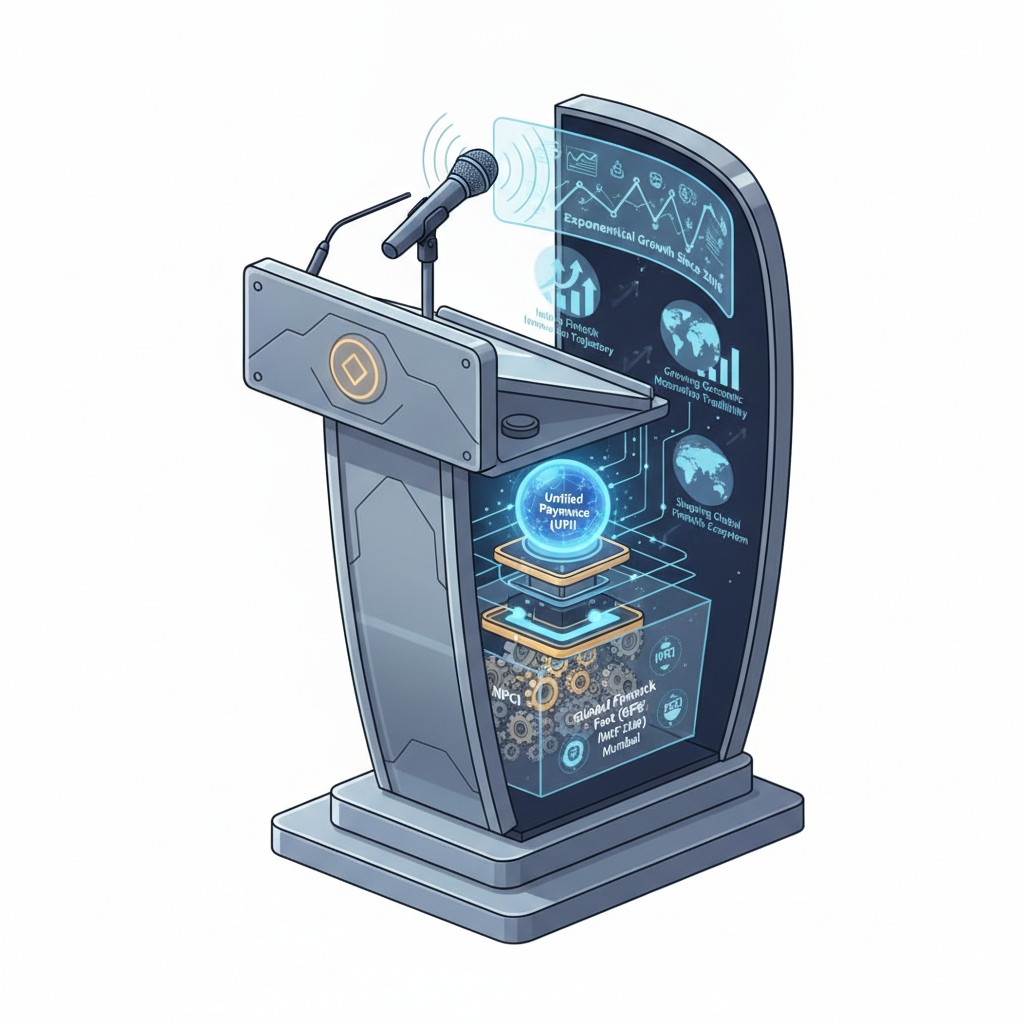
The Prime Minister of India addressed the inauguration of the Global Fintech Fest (GFF) 2026 in Mumbai, highlighting India’s trajectory in fintech innovation, the transformative impact of the Unified Payments Interface (UPI), and the country’s growing macroeconomic credibility. The address underscored India’s role in shaping the global fintech ecosystem amid geopolitical uncertainties and supply chain disruptions.
Background
- The Global Fintech Fest (GFF) is an annual event co-organised by the National Payments Corporation of India (NPCI), the Payments Council of India (PCI), and the Fintech Convergence Council (FCC) to foster collaboration among fintech innovators, regulators, and investors.
- India’s fintech sector has witnessed exponential growth since 2016, driven by digital public infrastructure initiatives such as UPI, Aadhaar-enabled payments, and the India Stack.
- The Reserve Bank of India (RBI) has played a pivotal role in regulating and promoting fintech innovation through frameworks like the Regulatory Sandbox and guidelines for digital lending.
- India’s macroeconomic stability has been reinforced by structural reforms, including the Insolvency and Bankruptcy Code (IBC), Goods and Services Tax (GST), and direct benefit transfers (DBT).
- The sovereign credit rating upgrade by Japan Credit Rating Agency (JCR) to ‘A’ category reflects international confidence in India’s growth momentum and policy reforms.
Key Dimensions of India’s Fintech Ecosystem and the Global Fintech Fest (GFF) 2026
- Unified Payments Interface (UPI): A real-time payment system developed by NPCI, enabling seamless inter-bank transactions via mobile devices. UPI has democratised financial access, particularly for underserved populations.
- Digital Public Infrastructure (DPI): India’s DPI, comprising Aadhaar, UPI, and the India Stack, has enabled frictionless financial inclusion and reduced transaction costs, serving as a model for other developing nations.
- Global Expansion of UPI: UPI is now operational in 11 countries, including Singapore, UAE, and France, facilitating cross-border remittances and payments. This expansion reflects India’s leadership in global fintech innovation.
- Macroeconomic Stability and Sovereign Ratings: India’s sovereign credit rating upgrade by JCR to ‘A’ category underscores its resilience amid global economic uncertainties, attributed to structural reforms and fiscal discipline.
- Fintech Innovation and Risk-Taking: The fintech sector in India has fostered a culture of entrepreneurship, with startups and established firms driving solutions in digital lending, wealth management, and blockchain-based services.
- Regulatory Framework: The RBI’s proactive approach, including the Regulatory Sandbox and guidelines for digital lending, has balanced innovation with consumer protection and systemic stability.
- Cultural and Economic Synergy: The timing of GFF 2026, coinciding with Ganesh Chaturthi in Maharashtra, symbolises the integration of India’s cultural ethos with technological progress, reinforcing the theme of ‘Viksit Bharat’ (Developed India).
- Challenges Ahead: Despite progress, challenges such as cybersecurity risks, data privacy concerns, and the need for interoperability across global payment systems remain critical for sustained growth.
Key Features
| Feature | Significance |
|---|---|
| Global Fintech Fest (GFF) 2026 | A premier international platform for fintech innovation, policy dialogue, and investment, fostering cross-border collaboration and showcasing India’s fintech leadership. |
| UPI’s Decadal Milestone (25 Aug 2026) | Demonstrates India’s transformative journey in digital payments, achieving 240 crore transactions in August 2026 alone, with an average of 50 lakh transactions every 10 minutes. |
| Sovereign Credit Rating Upgrade (Japan Credit Rating Agency, 2026) | India’s sovereign rating upgraded to ‘A’ category after three decades, reflecting macroeconomic stability, structural reforms, and global confidence in India’s growth momentum. |
| UPI’s Global Expansion (11 Countries) | UPI’s cross-border adoption in 11 countries validates India’s fintech prowess, enabling seamless cross-border payments and financial inclusion. |
| Fintech-Driven Financial Inclusion | UPI has enabled millions of previously unbanked Indians to become active participants in the formal financial ecosystem, redefining traditional banking paradigms. |
Why it Matters
Economic Growth and Stability
- India’s GDP growth of 7.8% in Q1 2026 underscores resilience amid global economic uncertainty, trade tensions, and supply chain disruptions.
- Structural reforms (e.g., GST, IBC, PLI schemes) have enhanced macroeconomic stability, attracting sovereign rating upgrades and foreign investment.
- Fintech-driven financial inclusion has expanded the tax base, reduced leakages, and improved monetary policy transmission.
Strategic and Geopolitical
- UPI’s global adoption positions India as a leader in digital public infrastructure (DPI), influencing global fintech standards and payment systems.
- Sovereign rating upgrades enhance India’s credibility in international forums, facilitating easier access to global capital markets.
- Cross-border fintech collaborations (e.g., UPI in 11 countries) strengthen economic diplomacy and soft power.
Technological and Innovation Leadership
- India’s fintech ecosystem (UPI, Aadhaar, DigiLocker) exemplifies the ‘India Stack’ model, combining technology with governance for inclusive growth.
- The ‘risk-taking capacity’ and ‘bold dreams’ of Indian entrepreneurs reflect a shift toward innovation-driven economic growth.
- GFF 2026 serves as a catalyst for policy innovation, investment, and knowledge exchange in fintech and allied sectors.
Social and Cultural Integration
- The alignment of fintech innovation (GFF 2026) with cultural events (Ganeshotsav) highlights India’s unique approach to blending tradition with modernity.
- Digital public infrastructure (DPI) has democratised access to financial services, bridging urban-rural divides and fostering social equity.
Challenges
1. Cybersecurity and Data Privacy
- Rapid digitisation increases exposure to cyber threats, necessitating robust frameworks under the Digital Personal Data Protection Act, 2023.
- Cross-border fintech operations require harmonised data governance standards to prevent regulatory arbitrage.
- Ensuring real-time fraud detection and redressal mechanisms for UPI and other fintech platforms.
UPSC Link: GS3: Cybersecurity, Digital Governance
2. Regulatory Harmonisation
- Fragmented regulatory oversight across RBI, SEBI, and other bodies may lead to compliance burdens for fintech firms.
- Need for a unified fintech regulatory sandbox to encourage innovation while mitigating systemic risks.
- Balancing innovation with consumer protection in rapidly evolving fintech models (e.g., BNPL, DeFi).
UPSC Link: GS2: Regulatory Bodies, Financial Sector
3. Digital Divide and Accessibility
- Ensuring last-mile connectivity and digital literacy in rural and underserved regions to prevent exclusion.
- Addressing the needs of differently-abled users in fintech interfaces and services.
- Promoting multilingual support in fintech platforms to cater to India’s linguistic diversity.
UPSC Link: GS1: Social Justice, Digital Divide
4. Global Competition and Standardisation
- Competing with established global payment systems (e.g., SWIFT, Visa, Mastercard) while maintaining interoperability.
- Ensuring UPI’s compatibility with international standards (e.g., ISO 20022) for seamless cross-border transactions.
- Mitigating geopolitical risks in fintech collaborations (e.g., sanctions, trade barriers).
UPSC Link: GS2: International Relations, GS3: Technology
5. Sustainability and Ethical Fintech
- Addressing the environmental impact of digital infrastructure (e.g., data centres, blockchain energy consumption).
- Ensuring ethical AI and algorithmic transparency in fintech lending and credit scoring.
- Promoting green fintech initiatives (e.g., carbon credit platforms, ESG-compliant investments).
UPSC Link: GS3: Environment, Ethics in Governance
Challenges — UPSC Perspective
| Issue | Concern |
|---|---|
| Cybersecurity Threats | Increased vulnerability to data breaches, fraud, and ransomware attacks in digital payment systems. |
| Regulatory Fragmentation | Overlapping mandates of RBI, SEBI, and other bodies may hinder fintech innovation. |
| Digital Literacy Gaps | Low awareness and skills in rural areas could limit fintech adoption and inclusion. |
| Cross-Border Compliance | Divergent regulatory frameworks in partner countries may complicate UPI’s global expansion. |
| Ethical AI in Lending | Algorithmic bias in fintech credit scoring could exacerbate financial exclusion. |
| Sustainability of DPI | Energy-intensive digital infrastructure may conflict with India’s climate commitments. |
Government Initiatives — Must-Memorise for Prelims
- Digital Personal Data Protection Act, 2023
- Reserve Bank of India’s (RBI) Regulatory Sandbox Framework
- Payment Infrastructure Development Fund (PIDF) Scheme
- Pradhan Mantri Garib Kalyan Anna Yojana (PMGKAY) – for financial inclusion linkages
Way Forward
- Strengthen cybersecurity frameworks under the Digital Personal Data Protection Act, 2023, with real-time threat monitoring and public-private partnerships.
- Establish a unified fintech regulatory sandbox to encourage innovation while ensuring consumer protection and systemic stability.
- Expand digital literacy programs (e.g., ‘Digital Saksharta Abhiyan’) to bridge the rural-urban divide and promote inclusive fintech adoption.
- Accelerate cross-border fintech collaborations by harmonising data governance standards with partner countries (e.g., UAE, Singapore, France).
- Promote green fintech initiatives to align digital infrastructure with India’s climate goals, including energy-efficient data centres.
- Enhance UPI’s global interoperability by adopting international standards (e.g., ISO 20022) and expanding partnerships with central banks.
- Develop ethical AI guidelines for fintech lending to mitigate algorithmic bias and ensure fair access to credit.
- Leverage GFF 2026 to showcase India’s fintech model and attract foreign direct investment (FDI) in the sector.
UPSC Value Addition
Keywords for Mains Answer-Writing
Global Fintech Fest (GFF) 2026 · UPI · fintech ecosystem · digital public infrastructure · credit rating upgrade · sovereign rating · macroeconomic stability · structural reforms · financial inclusion · cross-border digital payments · G20 presidency · innovation in financial services · reserve bank of india (RBI) · financial sector governance · digital transformation of economy
Constitutional & Policy Linkages
- Article 21 (Right to Life and Personal Liberty) – Protection of digital rights and data privacy.
- Article 19(1)(g) (Freedom to Practise Any Profession) – Enables fintech entrepreneurship and innovation.
- Article 300A (Right to Property) – Safeguards digital assets and financial transactions.
Concept Flow
Global Economic Uncertainty → Supply Chain Disruptions → Trade Tensions → India’s 7.8% GDP Growth (Q1 2026) → Sovereign Rating Upgrade → Global Confidence in India → Fintech Innovation (UPI) → Digital Public Infrastructure (India Stack) → Financial Inclusion → Economic Growth → Global Adoption (11 Countries) → Structural Reforms (GST, IBC, PLI) → Macroeconomic Stability → Foreign Investment → Sovereign Rating Upgrade → Enhanced Creditworthiness → Digital Payments (UPI) → Reduced Cash Dependency → Formalisation of Economy → Tax Base Expansion → Monetary Policy Efficiency → Cross-Border Fintech (UPI) → Economic Diplomacy → Soft Power → Global Standardisation → Interoperability → GFF 2026 → Policy Dialogue → Investment Flows → Innovation Ecosystem → India as Fintech Leader → Cultural Integration (Ganeshotsav) → Social Acceptance → Digital Adoption → Inclusive Growth
Prelims Practice Questions
Q1. Consider the following statements regarding the Unified Payments Interface (UPI):
1. UPI was launched in 2016.
2. UPI enables inter-bank peer-to-peer and person-to-merchant transactions in real time.
3. UPI transactions are processed by the National Payments Corporation of India (NPCI).
4. UPI is currently operational in only one foreign country.
How many of the above statements are correct?
- Only one
- Only two
- Only three
- All
Answer: All — Statements 1, 2, and 3 are correct. UPI was launched on 11 April 2016, enables real-time inter-bank transactions, and is operated by NPCI. Statement 4 is incorrect as UPI is live in 11 countries as of 2026.
Q2. Assertion (A): The Reserve Bank of India (RBI) is the sole regulator of the fintech sector in India.
Reason (R) : The RBI Act, 1934 empowers the RBI to regulate all financial entities including fintech companies.
Options:
A. Both A and R are true, and R is the correct explanation of A.
B. Both A and R are true, but R is NOT the correct explanation of A.
C. A is true, but R is false.
D. A is false, but R is true.
Answer: ? — Assertion (A) is false as the RBI is not the sole regulator; SEBI, IRDAI, and other sectoral regulators also oversee fintech entities in their domains. Reason (R) is true as the RBI Act, 1934 does empower the RBI, but it does not cover all fintech entities.
Q3. Match the following pairs regarding India’s sovereign credit ratings as of 2026:
Column I (Agency) | Column II (Rating Category)
———————————|—————————–
A. Japan Credit Rating Agency | 1. BBB-
B. S&P Global Ratings | 2. BBB
C. Moody’s Investors Service | 3. Baa3
D. Fitch Ratings | 4. BBB+
Options:
A. A-4, B-2, C-3, D-1
B. A-1, B-2, C-3, D-4
C. A-4, B-2, C-1, D-3
D. A-2, B-4, C-3, D-1
Answer: ? — As of 2026, Japan Credit Rating Agency upgraded India to A- (BBB+), S&P Global Ratings rates India at BBB, Moody’s at Baa3, and Fitch Ratings at BBB-. The correct match is A-4, B-2, C-3, D-1.
Mains Practice Question
✍ The Prime Minister, in his address at the Global Fintech Fest 2026, highlighted India’s fintech transformation through UPI and its macroeconomic stability. Critically examine the role of digital public infrastructure (DPI) in India’s economic development, with particular reference to UPI and its global expansion. Also, discuss the implications of India’s sovereign credit rating upgrade for its financial governance and investor confidence. (15 Marks)
Approach: MODEL-ANSWER SKELETON:
1. **Introduction (2 Marks)**
– Define Digital Public Infrastructure (DPI) as a foundational technology stack enabling inclusive and efficient public service delivery (e.g., Aadhaar, UPI, DigiLocker).
– Contextualise UPI as a flagship DPI in financial services.
2. **UPI as a Catalyst for Financial Inclusion (4 Marks)**
– Explain UPI’s mechanism: interoperable, real-time, low-cost transactions across banks via NPCI.
– Data: 2400+ crore transactions in August 2026; 10-year journey from 0 to 11 countries.
– Impact: Bridging the digital divide; enabling last-mile access for unbanked populations (e.g., PMJDY accounts).
– Cite the PM’s statement on ‘bank on fingertips’ and its empirical validation.
3. **Global Expansion and Cross-Border Payments (3 Marks)**
– List countries where UPI is live (e.g., Singapore, UAE, France).
– Discuss the significance: reducing reliance on SWIFT, enhancing India’s soft power in fintech diplomacy.
– Reference President Macron’s statement on UPI as a ‘civilisational story’.
4. **Macroeconomic Stability and Sovereign Ratings (3 Marks)**
– Explain sovereign credit ratings: Japan Credit Rating Agency’s upgrade to A- (BBB+) after 30 years.
– Link to India’s growth momentum (7.8% in Q1 2026), structural reforms (e.g., GST, IBC), and macroeconomic stability.
– Discuss how ratings influence FDI, cost of borrowing, and investor sentiment.
5. **Challenges and Governance Implications (3 Marks)**
– Challenges: Cybersecurity risks, data privacy (PDP Act, 2023), regulatory arbitrage, and interoperability with legacy systems.
– Governance: Role of RBI (e.g., NPCI oversight), SEBI for fintech regulations, and the need for a unified fintech policy.
– Conclude with a balanced view: DPI as a growth enabler but requiring robust safeguards.
Source: PIB (Press Information Bureau)
Maharashtra PCS (MPSC) — State PCS Practice
Prelims: Which of the following key initiatives was highlighted by the Prime Minister during the inaugural address at the Global Fintech Fest (GFF) 2026 in Mumbai, as per the official transcript?
- A. Launch of a national digital currency (CBDC) for retail transactions
- B. Introduction of a unified payment interface (UPI) for cross-border remittances
- C. Establishment of a dedicated ‘Mumbai Fintech Hub’ under the ‘Make in India’ initiative
- D. Announcement of a 100% tax exemption for fintech startups for the next 5 years
Answer: B. Introduction of a unified payment interface (UPI) for cross-border remittances — The Prime Minister emphasized the integration of UPI for cross-border remittances to enhance global fintech connectivity, as outlined in the GFF 2026 inaugural address.
Mains: Analyze the potential socio-economic impact of the Prime Minister’s announcement regarding the integration of UPI for cross-border remittances, with specific reference to Maharashtra’s fintech ecosystem and its role in India’s digital economy. Discuss the challenges and opportunities for MSMEs and migrant workers in Maharashtra in this context.
Generated by AanyaAi for educational purpose.
Related guides on our sites
- Current affairs for upsc 2026
- Best economics optional coaching for upsc
- Best economics optional teacher for upsc
- How to prepare for GS paper 1 for UPSC CSE mains exam

- मानसून सत्र: ओडिशा विधानसभा में विपक्ष का प्रमुख मुद्दा एमएमडीआर बिल - September 19, 2026
- Odisha Assembly Monsoon Session: MMDR Bill Withdrawal Key Demand - September 19, 2026
- मध्य प्रदेश में स्वास्थ्य सेवाओं का विस्तार: पीपीपी मॉडल और एमबीबीएस सीटों में वृद्धि - September 19, 2026
No Comments