
07 Oct RBI Auction Results: Key Cuts in 91/182/364-Day T-Bill Yields Explained for UPSC
✎ Treasury Bills (T-Bills) are zero-coupon government securities issued at a discount, with yields derived from auctions serving as benchmarks for short-term interest rates and liquidity management.
Subject Relevance — Where This Topic Fits
- GS Paper III — Indian Economy: Money and Banking, Government Borrowing, Monetary Policy Instruments
- Prelims: Treasury Bills (T-Bills), Yield to Maturity (YTM), Open Market Operations (OMO), Statutory Liquidity Ratio (SLR), Fiscal Deficit, Market Stabilisation Scheme (MSS)
- Essay: The role of government securities in managing fiscal deficits and monetary policy, The interplay between fiscal prudence and liquidity management in emerging economies
Quick Revision: Treasury Bills (T-Bills) are zero-coupon government securities issued at a discount, with yields derived from auctions serving as benchmarks for short-term interest rates and liquidity management.
Why is this in the news?
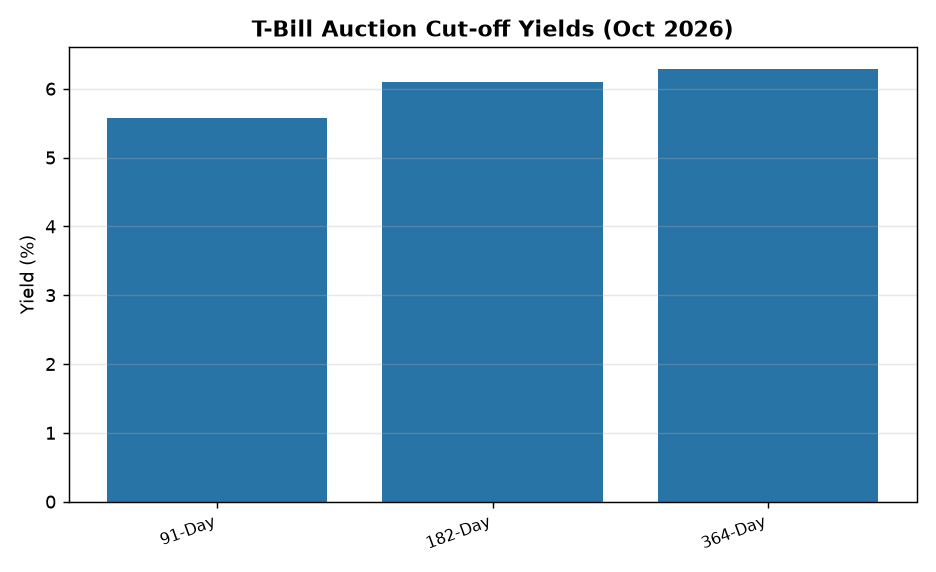
The Reserve Bank of India (RBI) conducted auctions for 91-day, 182-day, and 364-day Treasury Bills (T-Bills) on 7 October 2026, with cut-off prices indicating implicit yields of 5.5747%, 6.0999%, and 6.2869% respectively. These results reflect current market expectations regarding liquidity conditions, inflation dynamics, and the RBI’s monetary policy stance, making them significant for understanding the trajectory of short-term interest rates and government borrowing costs.
Background
- Treasury Bills (T-Bills) are short-term government securities issued by the RBI on behalf of the Government of India to meet its short-term funding requirements.
- T-Bills are issued at a discount to their face value and redeemed at par, with the difference representing the interest earned by investors.
- The RBI conducts regular auctions for T-Bills of varying maturities (91-day, 182-day, and 364-day) to manage liquidity in the banking system and meet the government’s fiscal needs.
- Yield to Maturity (YTM) is a key metric derived from T-Bill auctions, reflecting the annualised return an investor would earn if the bill is held to maturity.
- The RBI’s auction results are closely monitored by financial markets as they provide insights into the central bank’s liquidity management and the government’s borrowing strategy.
- The notified face values for the auctions (₹8,000 crore each for 91-day and 182-day T-Bills, and ₹7,000 crore for the 364-day T-Bill) indicate the government’s short-term borrowing requirements for the period.
What are Treasury Bills (T-Bills)?
- T-Bills are zero-coupon securities issued by the Government of India, meaning they do not pay periodic interest but are issued at a discount to their face value.
- They are issued in three standard maturities: 91 days, 182 days, and 364 days, catering to short-term liquidity needs of the government.
- T-Bills are auctioned by the RBI on behalf of the government, with the cut-off price determining the yield to maturity (YTM) for successful bidders.
- Investors in T-Bills include commercial banks, primary dealers, mutual funds, insurance companies, and non-resident investors, reflecting their role in the broader financial system.
- T-Bills are considered risk-free instruments as they are backed by the sovereign guarantee of the Government of India, making them a preferred choice for liquidity management.
- The YTM derived from T-Bill auctions serves as a benchmark for short-term interest rates in the economy, influencing lending and deposit rates in the banking system.
- T-Bills are also used by the RBI as part of its Open Market Operations (OMO) to manage liquidity in the banking system and align it with the monetary policy stance.
- The auction process for T-Bills follows a uniform price auction mechanism, where all successful bidders receive securities at the same cut-off price, ensuring fairness and transparency.
Key Features
| Feature | Significance |
|---|---|
| Tenor of T-Bills (91-Day, 182-Day, 364-Day) | Provides short-term government securities with maturities ranging from 3 months to 1 year, catering to liquidity management needs of banks and institutional investors. |
| Cut-off Price and Implicit Yield | Determines the price at which bids are accepted and the yield-to-maturity (YTM) for investors, reflecting market demand and liquidity conditions. |
| Total Face Value Notified (₹8,000 Crore, ₹8,000 Crore, ₹7,000 Crore) | Indicates the quantum of government borrowing through T-Bills, influencing the fiscal deficit and monetary policy stance. |
| Full Allotment of Notified Amount | Signals robust investor appetite for sovereign paper, reducing the need for open market operations or liquidity injections by the central bank. |
Why it Matters
Monetary Policy Transmission
- The implicit yields on T-Bills serve as a benchmark for pricing short-term commercial paper, corporate bonds, and bank lending rates, thereby influencing broader credit conditions.
- Yields on 364-day T-Bills are particularly critical as they approximate the policy rate corridor, providing insights into market expectations of future interest rate movements.
- Higher yields at longer tenors may signal tightening liquidity conditions or elevated inflation expectations, prompting the central bank to adjust its liquidity management tools.
Fiscal Management
- T-Bill auctions are a primary instrument for the government to finance its fiscal deficit in a non-inflationary manner, reducing reliance on long-term borrowings.
- The notified amounts align with the government’s cash flow requirements and the Union Budget’s gross market borrowing estimates, ensuring fiscal discipline.
- Full subscription of notified amounts indicates strong investor confidence in sovereign debt, reducing the cost of borrowing for the exchequer.
Market Liquidity and Investor Sentiment
- T-Bills are highly liquid instruments, traded in the secondary market, and form a critical component of the liquidity coverage ratio (LCR) for banks.
- The yields reflect the risk-free rate in the economy, influencing portfolio allocations by mutual funds, insurance companies, and foreign portfolio investors.
- A steepening yield curve (higher yields at longer tenors) may indicate expectations of tighter monetary policy, while a flatter curve suggests stable or easing conditions.
Macroeconomic Indicators
- Short-term yields are sensitive to liquidity conditions, inflation trends, and global financial market movements, serving as a leading indicator of economic stress.
- The spread between T-Bill yields and policy rates (repo rate) provides insights into the effectiveness of monetary policy transmission.
- Persistent high yields may reflect concerns over fiscal sustainability or external sector vulnerabilities, warranting closer scrutiny by policymakers.
Challenges
1. Liquidity Management Challenges
- Balancing the supply of T-Bills with market demand to avoid excessive volatility in short-term interest rates.
- Ensuring adequate participation from diverse investor segments (banks, mutual funds, FPIs) to maintain a liquid secondary market.
- Mitigating the impact of global financial shocks (e.g., US Fed rate hikes) on domestic T-Bill yields and investor sentiment.
UPSC Link: Monetary Policy Framework (RBI Act, 1934)
2. Fiscal Discipline and Borrowing Costs
- Managing the fiscal deficit within the glide path set by the FRBM Act while minimizing the cost of borrowing through optimal tenor mix.
- Avoiding over-reliance on short-term borrowings, which could expose the government to rollover risks in an adverse interest rate environment.
- Ensuring transparency and predictability in T-Bill issuance to build investor trust and reduce risk premiums.
UPSC Link: Fiscal Responsibility and Budget Management (FRBM) Act, 2003
3. Market Depth and Investor Confidence
- Enhancing the depth of the secondary market for T-Bills to improve price discovery and reduce bid-ask spreads.
- Addressing structural issues such as concentration of holdings among a few large investors, which could distort market dynamics.
- Promoting retail participation in T-Bills through simplified access mechanisms (e.g., RBI Retail Direct Scheme) to broaden the investor base.
UPSC Link: Financial Market Regulations (SEBI/RBI Guidelines)
Challenges — UPSC Perspective
| Issue | Concern |
|---|---|
| Excessive Volatility in Yields | Disrupts monetary policy transmission and increases uncertainty for borrowers and lenders. |
| Overlapping Tenors and Investor Preferences | May lead to uneven demand distribution, causing inefficiencies in liquidity management. |
| Global Spillovers (e.g., US Fed Policy) | Can trigger sudden shifts in investor sentiment, leading to capital outflows or higher borrowing costs. |
| Fiscal-Monetary Policy Coordination | Ensuring that T-Bill issuance does not conflict with the central bank’s liquidity objectives or inflation targets. |
| Secondary Market Fragmentation | Limited trading activity in T-Bills outside primary auctions increases systemic risk and reduces market resilience. |
Way Forward
- Enhance the secondary market for T-Bills by incentivizing market makers and promoting electronic trading platforms to improve liquidity.
- Diversify the investor base through targeted outreach to retail investors, pension funds, and insurance companies via the RBI Retail Direct Scheme.
- Strengthen coordination between the Ministry of Finance and the RBI to align T-Bill issuance with monetary policy objectives and fiscal needs.
- Introduce flexible issuance mechanisms (e.g., variable rate auctions) to adapt to changing market conditions and investor preferences.
- Monitor global financial conditions and domestic macroeconomic indicators to preemptively adjust T-Bill supply and tenor mix.
- Publish detailed post-auction reports to enhance transparency and build investor confidence in the T-Bill market.
- Explore the introduction of green or sovereign social bonds alongside T-Bills to cater to ESG-focused investors and diversify funding sources.
UPSC Value Addition
Keywords for Mains Answer-Writing
Treasury Bills · Yield to Maturity · Monetary Policy Instruments · Government Securities Market · Yield Curve · Discount Instruments · Liquidity Management · Reserve Bank of India · Public Debt Management · Fiscal Policy Coordination · Money Markets · Risk-Free Rate · Auction Mechanism · Cut-off Yield · Debt Instruments · Short-Term Borrowing
Concept Flow
Government’s fiscal deficit → Requires market borrowing → T-Bill issuance as a short-term instrument → Auction process determines yields and cut-off prices. → Investor demand for T-Bills → Reflects liquidity conditions and risk-free rate expectations → Influences broader credit markets and policy transmission. → RBI’s liquidity management → Adjusts repo rate and open market operations → Affects T-Bill yields and investor sentiment. → Global financial conditions → Impact capital flows and investor appetite → May lead to volatility in domestic T-Bill yields. → Fiscal Responsibility and Budget Management (FRBM) Act → Guides borrowing limits and deficit targets → Ensures sustainable T-Bill issuance.
Prelims Practice Questions
Q1. Consider the following statements regarding Treasury Bills (T-Bills) in India:
1. T-Bills are issued by the Government of India to meet short-term liquidity requirements.
2. T-Bills are zero-coupon securities and are issued at a discount to face value.
3. The yield on T-Bills is determined through a uniform price auction mechanism.
4. T-Bills are tradable in the secondary market and are eligible for Statutory Liquidity Ratio (SLR) compliance.
How many of the above statements are correct?
- Only one
- Only two
- Only three
- All four
Answer: All four — Statements 1, 2, and 4 are correct. Statement 3 is incorrect because T-Bills are issued through a multiple price auction mechanism, not a uniform price auction.
Q2. Assertion (A): The implicit yield on a Treasury Bill is higher than the coupon rate of a Government Bond of the same maturity.
Reason (R): Treasury Bills are issued at a discount and do not carry periodic interest payments, whereas Government Bonds pay periodic coupons.
Options:
A. Both A and R are true, and R is the correct explanation of A.
B. Both A and R are true, but R is not the correct explanation of A.
C. A is true, but R is false.
D. A is false, but R is true.
Answer: ? — Both A and R are true. The implicit yield on a T-Bill is calculated based on the discount at which it is issued, and since T-Bills do not pay periodic coupons, their yield is inherently higher than the coupon rate of a Government Bond of the same maturity.
Q3. Match the following columns related to Government Securities in India:
Column I (Type of Security) | Column II (Characteristic)
1. Treasury Bills (T-Bills) | A. Long-term securities with fixed coupon rates
2. Government Bonds (G-Secs) | B. Zero-coupon securities issued at a discount
3. State Development Loans (SDLs) | C. Issued by State Governments for developmental purposes
4. Cash Management Bills (CMBs) | D. Short-term instruments issued to manage cash flow mismatches
Options:
A. 1-B, 2-A, 3-C, 4-D
B. 1-A, 2-B, 3-C, 4-D
C. 1-D, 2-A, 3-B, 4-C
D. 1-C, 2-B, 3-A, 4-D
Answer: ? — The correct match is: 1-B (T-Bills are zero-coupon securities issued at a discount), 2-A (Government Bonds are long-term securities with fixed coupon rates), 3-C (SDLs are issued by State Governments for developmental purposes), and 4-D (CMBs are short-term instruments issued to manage cash flow mismatches).
Mains Practice Question
✍ The yield curve for Government securities, particularly Treasury Bills (T-Bills), serves as a critical benchmark for monetary policy and financial market dynamics in India. In light of the recent auction results for 91-Day, 182-Day, and 364-Day T-Bills, critically examine the significance of T-Bills in India’s public debt management and monetary policy framework. Also, discuss the implications of rising implicit yields on these instruments for fiscal sustainability and inflation expectations. (15 Marks)
Approach: MODEL-ANSWER SKELETON:
1. **Introduction to T-Bills**: Define T-Bills as zero-coupon, discount instruments issued by the Government of India to meet short-term borrowing requirements. Mention their role as a key instrument in the Government Securities (G-Sec) market.
2. **Auction Mechanism and Yield Determination**: Explain the multiple price auction mechanism used by the Reserve Bank of India (RBI) for issuing T-Bills. Describe how the cut-off yield (implicit yield) is determined and its significance in reflecting market expectations.
3. **Role in Monetary Policy**: Discuss how T-Bills serve as a benchmark for short-term interest rates and their use in liquidity management by the RBI. Highlight their role in the transmission of monetary policy signals to the broader economy.
4. **Public Debt Management**: Analyse how T-Bills contribute to the Government’s short-term borrowing strategy and their impact on the overall debt profile. Discuss the trade-offs between short-term borrowing (T-Bills) and long-term borrowing (Government Bonds).
5. **Implications of Rising Yields**: Examine the consequences of rising implicit yields on T-Bills for fiscal sustainability, including the cost of servicing debt. Discuss how higher yields may signal inflation expectations or tightening liquidity conditions.
6. **Secondary Market Dynamics**: Briefly touch upon the tradability of T-Bills in the secondary market and their role in meeting Statutory Liquidity Ratio (SLR) requirements for banks.
7. **Conclusion**: Summarise the critical role of T-Bills in India’s financial ecosystem and the importance of monitoring yield trends for macroeconomic stability.
Source: RBI
Generated by AanyaAi for educational purpose.
Related guides on our sites
- Best PSIR optional coaching for upsc
- Best economics optional coaching for upsc
- Best PSIR optional teacher for upsc
- Best teacher of PSIR optional for upsc

No Comments