


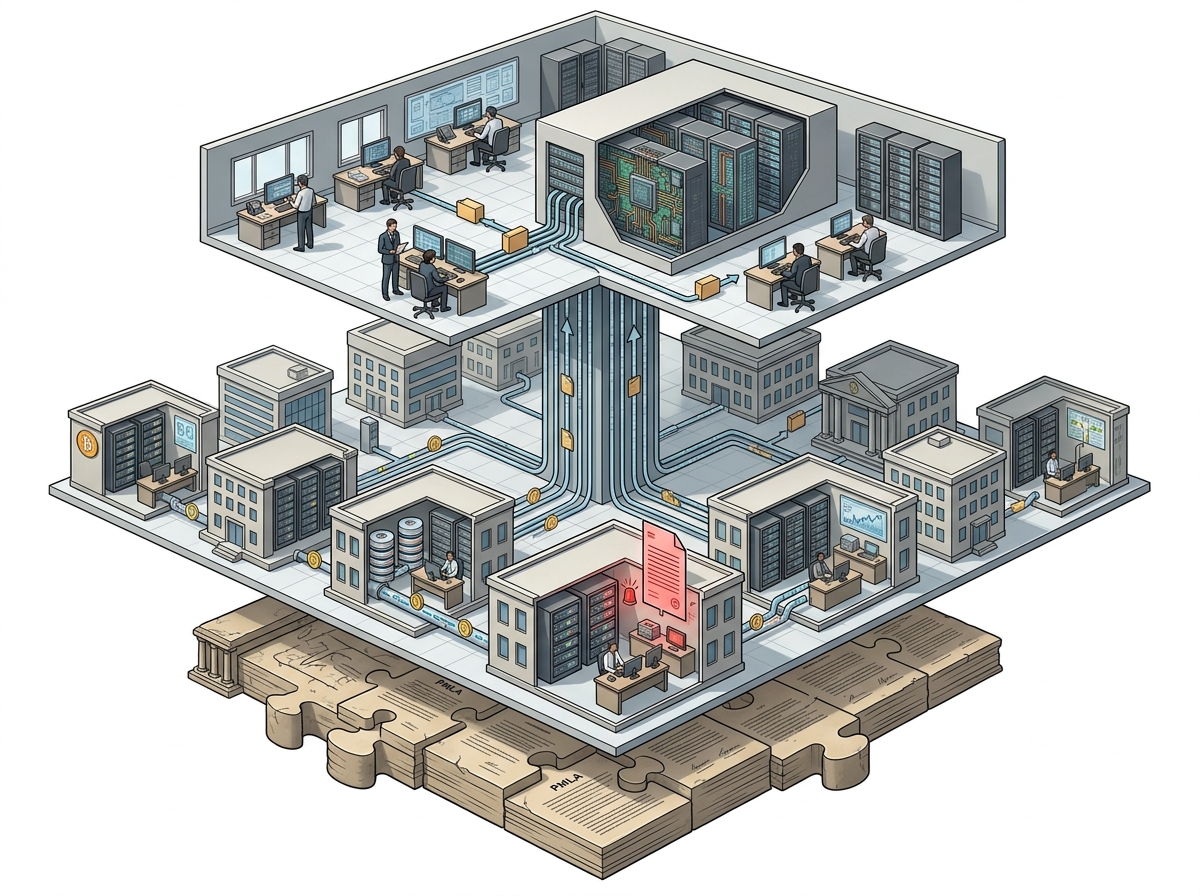
09 Sep FIU-IND issues notices to 15 crypto firms for PMLA non-compliance
✎ Virtual Digital Asset Service Providers (VDA-SPs) in India are now regulated under the PMLA, 2002 as reporting entities, requiring registration with FIU-IND and strict compliance with AML/CFT obligations.
Subject Relevance — Where This Topic Fits
- GS Paper III — Economy: Money Laundering, Financial Regulation, Digital Assets
- Prelims: PMLA, 2002, Financial Intelligence Unit – India (FIU-IND), Virtual Digital Assets (VDAs), Anti-Money Laundering (AML), CFT Framework, Section 13 of PMLA
- Essay: Regulatory challenges in the digital economy: Balancing innovation and financial integrity
Quick Revision: Virtual Digital Asset Service Providers (VDA-SPs) in India are now regulated under the PMLA, 2002 as reporting entities, requiring registration with FIU-IND and strict compliance with AML/CFT obligations.
Why is this in the news?
The Financial Intelligence Unit-India (FIU-IND) under the Ministry of Finance has issued compliance notices to 15 Virtual Digital Asset Service Providers (VDA-SPs) for non-adherence to the reporting obligations under Section 13 of the Prevention of Money Laundering Act (PMLA), 2002. This action underscores the expanding regulatory oversight of digital financial assets in India, aligning with global standards for anti-money laundering (AML) and counter-terrorism financing (CFT) frameworks. The development is significant as it highlights the government’s commitment to enforcing financial integrity in the rapidly evolving virtual asset ecosystem.
Background
- The PMLA, 2002 was enacted to prevent money laundering and enable confiscation of proceeds of crime. It mandates reporting entities to maintain records and furnish information to the Financial Intelligence Unit-India (FIU-IND).
- In March 2023, the Government of India notified Virtual Digital Assets (VDAs) and their service providers under the PMLA, bringing them within the ambit of AML/CFT regulations.
- VDAs include cryptocurrencies, non-fungible tokens (NFTs), and other digital representations of value, excluding Indian or foreign currencies.
- VDA-SPs are entities engaged in activities such as exchange between VDAs and fiat currencies, transfer of VDAs, safekeeping or administration of VDAs, and provision of financial services related to VDAs.
- The FIU-IND, established in 2004, is the central agency responsible for receiving, processing, analyzing, and disseminating information related to suspect financial transactions under the PMLA.
What are Virtual Digital Assets (VDAs) and their Regulatory Framework under PMLA?
- Virtual Digital Assets (VDAs) are defined under Section 2(47A) of the Income-tax Act, 1961, as any information, code, number, or token generated through cryptographic means, representing value and exchangeable with or without consideration.
- VDAs include cryptocurrencies (e.g., Bitcoin, Ethereum), utility tokens, non-fungible tokens (NFTs), and other digital representations of value, excluding Indian or foreign currencies.
- The PMLA, 2002 was amended in 2023 to include VDAs and VDA-SPs within its regulatory ambit, making them ‘reporting entities’ under Section 2(1)(sa) of the Act.
- VDA-SPs must register with the FIU-IND as reporting entities and comply with obligations such as maintaining records, reporting suspicious transactions (STRs), and implementing AML/CFT measures.
- The compliance obligations are activity-based and apply regardless of the physical presence of the entity in India, ensuring extraterritorial reach where activities impact the Indian financial system.
- The regulatory framework aims to mitigate risks of money laundering, terrorist financing, and other financial crimes associated with anonymous and borderless digital transactions.
- The enforcement action reflects India’s alignment with global standards set by the Financial Action Task Force (FATF) for regulating virtual assets and their service providers.
Key Features
| Feature | Significance |
|---|---|
| Regulatory scope under PMLA, 2002 | Virtual Digital Asset Service Providers (VDA SPs) are now explicitly brought under the anti-money laundering (AML) and counter-financing of terrorism (CFT) framework, ensuring parity with traditional financial institutions. |
| Reporting obligations to FIU-IND | VDA SPs must register with FIU-IND and submit Suspicious Transaction Reports (STRs), Cash Transaction Reports (CTRs), and other mandated disclosures to prevent illicit financial flows. |
| Geographic neutrality of compliance | Compliance obligations apply irrespective of the physical presence of the VDA SP in India, covering both onshore and offshore entities operating in the domestic market. |
| Intermediary liability under IT Rules, 2025 | VDA SPs are directed to remove non-compliant applications/URLs under IT Act, 2000, aligning digital asset regulation with intermediary due diligence standards. |
| Public risk communication | Regulatory advisories highlight the high-risk nature of crypto assets and NFTs, cautioning investors about the absence of regulatory safeguards for such transactions. |
Why it Matters
Financial System Integrity
- Prevents money laundering and terrorist financing through digital asset channels by enforcing AML/CFT protocols.
- Ensures transparency in cross-border crypto transactions, reducing opacity in virtual asset ecosystems.
- Strengthens India’s compliance with Financial Action Task Force (FATF) recommendations on virtual assets.
Regulatory Governance
- Establishes FIU-IND as the nodal authority for monitoring VDA transactions, centralising financial intelligence.
- Clarifies the legal framework for digital asset intermediaries, reducing regulatory arbitrage.
- Harmonises digital asset regulation with existing financial crime prevention mechanisms.
Consumer Protection
- Mandates disclosures and risk warnings to safeguard retail investors from high-risk crypto products.
- Enables traceability of illicit funds, aiding law enforcement in asset recovery.
- Discourages unregulated crypto platforms from operating in India, reducing exposure to fraud.
Challenges
1. Regulatory Arbitrage in Digital Assets
- Offshore VDA SPs may exploit jurisdictional gaps to bypass Indian compliance requirements.
- Rapid innovation in decentralised finance (DeFi) and peer-to-peer (P2P) trading complicates enforcement.
- Cross-border nature of crypto transactions necessitates international cooperation for effective regulation.
UPSC Link: GS3: Money Laundering & Financial Crimes
2. Technological Enforcement Gaps
- Anonymity-preserving technologies (e.g., privacy coins, mixers) hinder AML/CFT monitoring.
- Decentralised exchanges (DEXs) and non-custodial wallets operate outside traditional intermediary frameworks.
- Real-time transaction monitoring for high-frequency crypto trades remains technically challenging.
UPSC Link: GS3: Cyber Security & Digital Governance
3. Investor Awareness Deficit
- Retail investors often lack understanding of the risks associated with unregulated crypto assets.
- Misleading marketing by VDA SPs may exaggerate returns, leading to financial losses.
- Absence of investor grievance redressal mechanisms for crypto-related disputes.
UPSC Link: GS3: Financial Inclusion & Consumer Protection
4. Global Regulatory Fragmentation
- Divergent approaches to crypto regulation across jurisdictions create compliance complexities.
- Lack of a unified global framework for crypto taxation and reporting standards.
- Risk of regulatory arbitrage by entities shifting operations to jurisdictions with lax oversight.
UPSC Link: GS2: International Organisations & Financial Governance
Challenges — UPSC Perspective
| Issue | Concern |
|---|---|
| Offshore VDA SPs | Difficulty in enforcing compliance on entities operating outside India. |
| DeFi and P2P platforms | Lack of centralised intermediaries to enforce AML/CFT rules. |
| Privacy-enhancing technologies | Obscures transaction trails, impeding financial intelligence gathering. |
| High-frequency trading | Technical limitations in real-time monitoring of crypto transactions. |
| Investor mis-selling | Unregulated platforms may mislead investors about crypto asset risks. |
Way Forward
- Strengthen FIU-IND’s technological capabilities for real-time transaction monitoring and data analytics.
- Enhance international cooperation with FATF and other jurisdictions to address cross-border crypto risks.
- Mandate periodic audits of VDA SPs’ compliance with PMLA provisions.
- Develop a national digital asset registry to track regulated and unregulated entities.
- Launch investor education campaigns to highlight risks of unregulated crypto assets.
- Establish a dedicated grievance redressal mechanism for crypto-related disputes.
- Align crypto taxation policies with global standards to reduce regulatory arbitrage.
- Explore blockchain forensics tools to trace illicit crypto transactions.
UPSC Value Addition
Keywords for Mains Answer-Writing
Financial Intelligence Unit – India (FIU-IND) · Prevention of Money Laundering Act (PMLA), 2002 · Virtual Digital Assets (VDA) · Virtual Digital Asset Service Providers (VDA SPs) · Anti-Money Laundering/Counter-Terrorist Financing (AML/CFT) · Reporting Entity under PMLA · Section 13 of PMLA · Digital Asset Regulation · Cryptocurrency Compliance · Financial Integrity and Stability · Regulatory Arbitrage · Information Technology Act, 2000 · Intermediary Guidelines Rules, 2025 · Financial Action Task Force (FATF) · Risk-Based Approach to AML/CFT
Concept Flow
Virtual Digital Asset (VDA) transactions → Regulatory ambiguity → PMLA, 2002 amendment (2023) → FIU-IND oversight → Compliance obligations for VDA SPs → Enforcement action (notices) → Removal of non-compliant platforms → Strengthened AML/CFT framework → Enhanced financial system integrity.
Prelims Practice Questions
Q1. Consider the following statements regarding the Prevention of Money Laundering Act (PMLA), 2002:
1. The PMLA applies to Virtual Digital Asset Service Providers (VDA SPs) only if they have a physical presence in India.
2. Under the PMLA, reporting entities are required to maintain records of transactions for a minimum period of 5 years.
3. The Financial Intelligence Unit – India (FIU-IND) is empowered to issue notices for non-compliance under Section 13 of the PMLA.
How many of the above statements are correct?
- Only one
- Only two
- All three
- None
Answer: All three — Statement 1 is incorrect: The PMLA applies to VDA SPs regardless of their physical presence in India, as long as they are engaged in activities within the scope of the Act. Statement 2 is correct: Reporting entities must maintain records of transactions for a minimum of 5 years under the PMLA. Statement 3 is correct: FIU-IND is empowered to issue notices for non-compliance under Section 13 of the PMLA.
Q2. Assertion (A): The Prevention of Money Laundering Act (PMLA), 2002, was amended in March 2023 to include Virtual Digital Assets (VDAs) within its ambit.
Reason (R): The inclusion of VDAs under the PMLA was necessitated by the global Financial Action Task Force (FATF) standards to address risks of money laundering and terrorist financing.
Options:
A. Both A and R are true, and R is the correct explanation of A.
B. Both A and R are true, but R is not the correct explanation of A.
C. A is true, but R is false.
D. A is false, but R is true.
Answer: ? — Assertion (A) is true: The PMLA was amended in March 2023 to include Virtual Digital Assets (VDAs) within its regulatory framework. Reason (R) is also true and correctly explains the assertion, as the FATF standards require member jurisdictions to regulate VDAs to mitigate AML/CFT risks.
Q3. Match the following provisions of the Prevention of Money Laundering Act (PMLA), 2002 with their respective descriptions:
Column I (Provision) | Column II (Description)
1. Section 12 | A. Maintenance of records by reporting entities
2. Section 13 | B. Power of the Director, FIU-IND to issue directions for non-compliance
3. Section 15 | C. Obligation to furnish information to the Director, FIU-IND
4. Section 18 | D. Freezing of property involved in money laundering
- 1-A, 2-B, 3-C, 4-D; 1-B, 2-A, 3-D, 4-C; 1-C, 2-D, 3-A, 4-B; 1-D, 2-C, 3-B, 4-A
- answer_match_indexes_to_options_indexes_for_correct_answer_is_0
- explain_match_pairs_in_explain_field
- format_match
Answer: 1-A, 2-B, 3-C, 4-D; 1-B, 2-A, 3-D, 4-C; 1-C, 2-D, 3-A, 4-B; 1-D, 2-C, 3-B, 4-A — Section 12 of the PMLA pertains to the obligation of reporting entities to maintain records of transactions. Section 13 empowers the Director, FIU-IND to issue directions for non-compliance. Section 15 requires reporting entities to furnish information to the Director, FIU-IND. Section 18 empowers the competent authority to provisionally attach or freeze property involved in money laundering.
Mains Practice Question
✍ The inclusion of Virtual Digital Assets (VDAs) within the ambit of the Prevention of Money Laundering Act (PMLA), 2002, marks a significant evolution in India’s regulatory framework for financial integrity. Critically examine the rationale behind this regulatory expansion, with particular reference to the risks posed by VDAs in the context of money laundering and terrorist financing. Also, analyse the compliance obligations imposed on Virtual Digital Asset Service Providers (VDA SPs) under the PMLA and evaluate the effectiveness of the current enforcement mechanism. (15 Marks)
Approach: MODEL-ANSWER SKELETON:
1. **Rationale for Regulatory Expansion (4 marks)**
– **Global Standards**: Reference to FATF Recommendations (e.g., Recommendation 15 on Virtual Assets and Virtual Asset Service Providers) and India’s commitment to global AML/CFT frameworks.
– **Risks Posed by VDAs**: Highlight anonymity, cross-border transactions, lack of KYC/AML controls, and use in illicit financing (e.g., darknet markets, ransomware payments).
– **Policy Objectives**: Need for consumer protection, financial stability, and alignment with India’s G20 presidency priorities (2023) on crypto regulation.
– **Precedents**: Compare with other jurisdictions (e.g., EU’s MiCA Regulation, US FinCEN rules).
2. **Compliance Obligations under PMLA (5 marks)**
– **Registration**: Requirement for VDA SPs to register as reporting entities with FIU-IND.
– **AML/CFT Framework**: Mandatory implementation of Know Your Customer (KYC), transaction monitoring, suspicious activity reporting (SAR), and record-keeping (Section 12, PMLA).
– **Reporting Requirements**: Submission of Cash Transaction Reports (CTRs), Suspicious Transaction Reports (STRs), and Annual Reports to FIU-IND.
– **Risk-Based Approach**: Emphasis on proportionate measures based on the nature of VDA activities (e.g., exchanges, wallets, DeFi platforms).
3. **Enforcement Mechanism and Effectiveness (6 marks)**
– **FIU-IND’s Role**: Powers under Section 13 (issuance of directions, notices for non-compliance) and Section 18 (freezing of assets).
– **Recent Enforcement Actions**: Reference to the issuance of notices to 15 VDA SPs (as reported on 09 Sep 2026) for non-compliance, highlighting the proactive stance of regulators.
– **Challenges**: Cross-border nature of VDAs, jurisdictional arbitrage, technological sophistication of illicit actors, and resource constraints in enforcement.
– **Effectiveness Assessment**:
– **Strengths**: Alignment with FATF standards, deterrent effect of notices, and public awareness campaigns.
– **Limitations**: Low conviction rates under PMLA, delays in investigations, and gaps in inter-agency coordination (e.g., with CBI, ED, and state agencies).
– **Way Forward**: Proposals for a dedicated regulatory authority for VDAs (e.g., akin to SEBI for securities), enhanced technological surveillance, and international cooperation under FATF.
**Balanced Conclusion**: While the expansion of PMLA to VDAs is a progressive step, its effectiveness hinges on robust enforcement, technological adaptation, and global cooperation. The current framework is a necessary but not sufficient condition for addressing the risks posed by VDAs.
Source: PIB (Press Information Bureau)
Generated by AanyaAi for educational purpose.
Related guides on our sites
- Current affairs for upsc 2026
- Best PSIR optional coaching for upsc
- Best PSIR optional teacher for upsc
- Best teacher of PSIR optional for upsc

- KWML’s Feasibility Reports for Water Metro in 18 Cities: UPSC & PCS Insights - October 3, 2026
- ओडिशा में वन्यजीव अनुसंधान अनुदान कार्यक्रम शुरू, सिमिलिपाल में 300 कैमरे और बढ़ेंगे - October 3, 2026
- India Summons Pakistan High Commission Official Over Violation - October 3, 2026

No Comments