
30 Oct SGB 2019-20 Series VI: Redemption Price for Premature Redemption on Oct 30, 2026
✎ The Sovereign Gold Bond Scheme allows premature redemption after five years, with the redemption price determined by the simple average of the 999 purity gold price over the preceding three business days as published by IBJA.
Subject Relevance — Where This Topic Fits
- GS Paper III — Indian Economy: Money and Banking, Capital Markets
- Prelims: Sovereign Gold Bond Scheme, Gold Monetisation Scheme, IBJA gold price benchmarking, Government securities, Fifth-year redemption clause, 999 purity gold, RBI press release mechanism
- Essay: Role of gold in India’s financial system and macroeconomic stability, Financial inclusion through market-linked sovereign instruments
Quick Revision: The Sovereign Gold Bond Scheme allows premature redemption after five years, with the redemption price determined by the simple average of the 999 purity gold price over the preceding three business days as published by IBJA.
Why is this in the news?
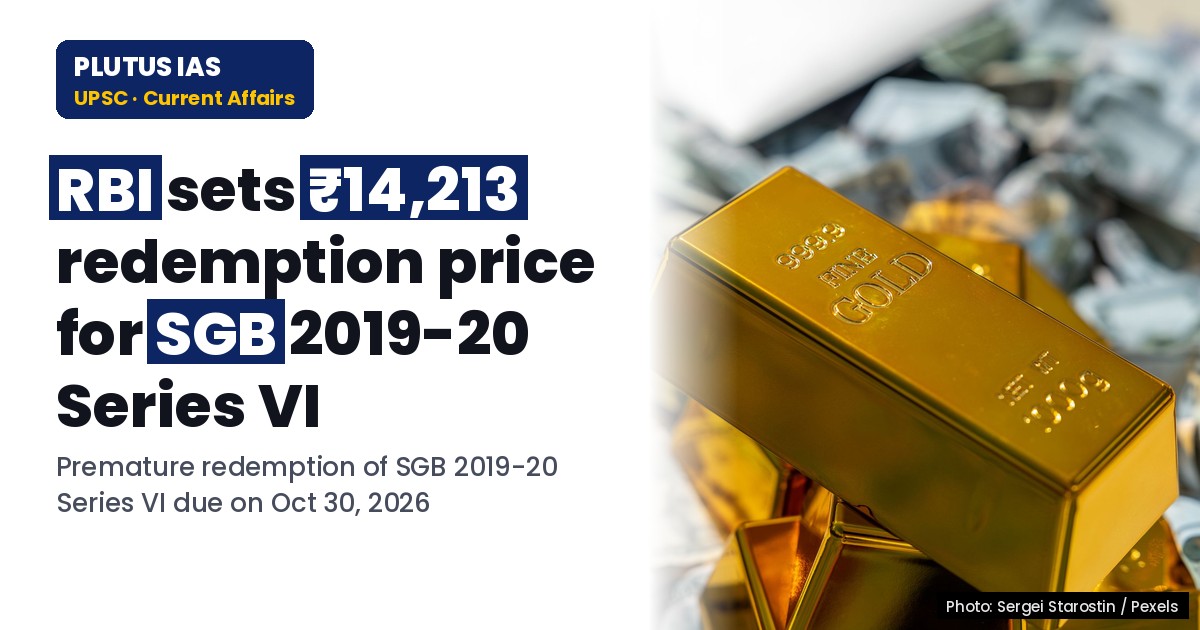
The Reserve Bank of India (RBI) has announced the redemption price for premature redemption of the Sovereign Gold Bond (SGB) 2019-20 Series VI on October 30, 2026, at ₹14,213 per unit. This follows the eligibility criteria permitting premature redemption after the completion of the fifth year from the date of issue, aligning with the terms of the Government of India notification dated September 30, 2019. The announcement underscores the operational transparency of the SGB scheme and the reliance on market-determined gold prices for valuation.
Background
- The Sovereign Gold Bond (SGB) Scheme was launched in 2015 by the Government of India in collaboration with the RBI to reduce the demand for physical gold and mobilise gold held by households into the financial system.
- The scheme offers an alternative investment avenue to individuals, trusts, and other entities, denominated in grams of gold with a fixed maturity period of eight years, though premature redemption is permitted after the fifth year.
- The SGB Scheme is part of broader efforts to develop the gold market in India, complementing initiatives like the Gold Monetisation Scheme (GMS) and the establishment of the India International Bullion Exchange (IIBX).
- Premature redemption is subject to specific conditions, including the completion of five years from the date of issue and the availability of redemption on interest payment dates.
- The redemption price is determined based on the simple average of the closing price of 999 purity gold over the three preceding business days, as published by the India Bullion and Jewellers Association Ltd (IBJA), ensuring market-linked valuation.
- The SGB Scheme is governed by the Government of India’s notification F.No. 4(7)-B(W&M)/2019 dated September 30, 2019, which outlines the terms, conditions, and operational guidelines for the issuance and redemption of bonds.
What is the Sovereign Gold Bond (SGB) Scheme?
- A government securities scheme launched in November 2015 to reduce physical gold holdings and promote financial savings.
- Issued by the Reserve Bank of India (RBI) on behalf of the Government of India, with denominations in grams of gold (e.g., 1 gram, 5 grams, etc.).
- Offers a fixed interest rate of 2.5% per annum on the issue price, payable semi-annually, providing a steady income stream to investors.
- The bonds have a maturity period of eight years, but premature redemption is permitted after the completion of the fifth year from the date of issue.
- Premature redemption is allowed only on specific dates coinciding with interest payment schedules, ensuring operational clarity and predictability for investors.
- The redemption price is calculated as the simple average of the closing price of 999 purity gold over the three business days preceding the redemption date, as published by the India Bullion and Jewellers Association Ltd (IBJA).
- Investors receive the redemption amount in Indian Rupees, eliminating the need for physical gold storage and associated risks.
- The scheme is open to resident individuals, Hindu Undivided Families (HUFs), trusts, universities, and charitable institutions, promoting broad-based participation in gold-backed financial instruments.
Key Features
| Feature | Significance |
|---|---|
| Premature Redemption Eligibility | Permits redemption after the fifth year from the issue date, providing liquidity flexibility to investors while maintaining long-term investment discipline. |
| Redemption Price Determination | Based on the simple average of the closing price of 999 purity gold over the three business days preceding redemption, ensuring transparency and market-linked valuation. |
| Issue Date and Series | SGB 2019-20 Series VI was issued on October 30, 2019, with the next premature redemption due on October 30, 2026, marking the seventh year of the scheme. |
| Government Notification Basis | Premature redemption is governed by the GOI notification F.No. 4(7)-B(W&M)/2019 dated September 30, 2019, which outlines the operational framework for the SGB scheme. |
| Price Calculation Mechanism | The redemption price of ₹14,213 per unit for October 30, 2026, is derived from the IBJA’s published gold prices, ensuring alignment with market conditions. |
Why it Matters
Financial Inclusion and Savings Mobilisation
- Provides an alternative to physical gold investment, reducing storage risks and enhancing financial inclusion by offering a sovereign-backed instrument.
- Encourages long-term savings in gold without the need for physical possession, aligning with the government’s objective of promoting financial literacy and asset diversification.
- Offers a hedge against inflation and currency depreciation, as gold prices are typically inversely correlated with the rupee’s value.
Monetary Policy and Gold Market Dynamics
- Reduces the demand for physical gold imports, thereby contributing to the stability of the current account and foreign exchange reserves.
- Enhances the depth and liquidity of the domestic gold market by providing a tradable sovereign instrument linked to gold prices.
- Supports the Reserve Bank of India’s (RBI) efforts to manage gold-related liquidity and price volatility in the domestic market.
Investor Protection and Transparency
- Ensures fair valuation through a transparent pricing mechanism based on IBJA’s benchmark gold prices, reducing arbitrage opportunities.
- Provides a secure and regulated investment avenue, mitigating risks associated with unregulated gold trading and counterfeit concerns.
- Offers tax benefits under Section 47(vii) of the Income-tax Act, 1961, for long-term capital gains if held till maturity, enhancing post-tax returns.
Fiscal Policy and Revenue Implications
- Generates non-tax revenue for the government through the issue and redemption of SGBs, contributing to fiscal consolidation efforts.
- Reduces the fiscal burden of gold imports by substituting physical gold with sovereign-backed instruments, thereby lowering the trade deficit.
Challenges
1. Liquidity Constraints for Early Redemption
- Premature redemption is permitted only after the fifth year, which may limit liquidity for investors requiring funds before this period.
- The redemption price is market-linked, which may result in lower returns if gold prices decline between the issue and redemption dates.
UPSC Link: GS-III: Financial Markets and Gold Policy
2. Price Volatility and Investor Risk
- Gold prices are subject to significant volatility due to global economic conditions, geopolitical factors, and currency fluctuations, exposing investors to market risks.
- The redemption price is based on a three-day average, which may not fully capture sudden price spikes or crashes, leading to suboptimal returns.
UPSC Link: GS-III: Commodity Markets and Price Stability
3. Awareness and Participation Gaps
- Limited awareness among retail investors about the SGB scheme’s features, benefits, and redemption mechanisms may hinder widespread adoption.
- The requirement for investors to hold the bonds for at least five years may deter short-term investors or those seeking immediate liquidity.
UPSC Link: GS-III: Financial Inclusion and Investor Education
4. Operational and Logistical Challenges
- The redemption process involves coordination between the RBI, depositories, and investors, which may lead to delays or procedural bottlenecks.
- Investors may face challenges in tracking the redemption price and ensuring timely submission of redemption requests.
UPSC Link: GS-III: Financial Sector Reforms and RBI Policies
Challenges — UPSC Perspective
| Issue | Concern |
|---|---|
| Liquidity Constraints | Premature redemption is restricted to the fifth year, limiting access to funds for early investors. |
| Market-Linked Pricing | Redemption price fluctuates with gold prices, exposing investors to volatility risks. |
| Awareness Deficit | Low participation due to insufficient knowledge about the scheme’s benefits and processes. |
| Operational Delays | Possible bottlenecks in the redemption process due to multi-stakeholder coordination. |
| Tax Implications | Capital gains tax applies if bonds are redeemed before maturity, reducing post-tax returns. |
| Counterparty Risk | Dependence on IBJA’s gold price data introduces a risk of pricing inaccuracies or delays. |
Government Initiatives — Must-Memorise for Prelims
- Sovereign Gold Bond (SGB) Scheme
Way Forward
- Enhance investor awareness campaigns to educate the public about the SGB scheme’s features, benefits, and redemption mechanisms.
- Explore the possibility of introducing partial premature redemption options to improve liquidity for investors.
- Strengthen the coordination between the RBI, depositories, and investors to streamline the redemption process and reduce delays.
- Conduct periodic reviews of the SGB scheme’s pricing mechanism to ensure it remains aligned with market conditions and investor expectations.
- Promote the use of digital platforms for SGB transactions to enhance accessibility and reduce operational bottlenecks.
- Study the impact of SGBs on gold imports and trade deficit to assess the scheme’s contribution to fiscal and monetary stability.
- Collaborate with financial institutions to offer advisory services on SGB investments, particularly for retail investors.
- Evaluate the feasibility of introducing tax incentives for early redemption to balance liquidity and fiscal objectives.
UPSC Value Addition
Keywords for Mains Answer-Writing
Sovereign Gold Bond Scheme · premature redemption of SGB · redemption price determination · India Bullion and Jewellers Association Ltd (IBJA) · financial instruments for gold investment · government securities · capital market instruments · gold price benchmarking · financial inclusion through gold bonds · monetisation of gold holdings
Concept Flow
Issue of SGB 2019-20 Series VI on October 30, 2019, under the Sovereign Gold Bond Scheme notified by the Government of India. → Investor holds the bond for a minimum of five years, with premature redemption permitted thereafter. → RBI announces the redemption price based on the simple average of IBJA’s gold prices over the three preceding business days. → Investor submits a redemption request, and the process is executed through the designated depository. → Redemption proceeds are credited to the investor’s bank account, completing the transaction. → The scheme’s design ensures market-linked returns, fiscal benefits, and reduced reliance on physical gold imports.
Prelims Practice Questions
Q1. Consider the following statements regarding the Sovereign Gold Bond (SGB) Scheme:
1. Premature redemption is permitted after the fifth year from the date of issue.
2. The redemption price is based on the average of the closing price of gold for the three business days preceding the redemption date.
3. The redemption price is published by the Reserve Bank of India directly without any external benchmark.
How many of the above statements are correct?
- Only one
- Only two
- All three
- None
Answer: Only two — Statements 1 and 2 are correct as per the SGB Scheme guidelines. Statement 3 is incorrect because the redemption price is based on the simple average of the closing price of gold of 999 purity published by the India Bullion and Jewellers Association Ltd (IBJA).
Q2. Assertion (A): The Sovereign Gold Bond Scheme allows investors to redeem their bonds prematurely after the fifth year from the date of issue.
Reason (R): This provision is designed to provide liquidity to investors while ensuring the long-term holding of gold in the economy.
Options:
A. Both A and R are true, and R is the correct explanation of A.
B. Both A and R are true, but R is not the correct explanation of A.
C. A is true, but R is false.
D. A is false, but R is true.
Answer: ? — Assertion (A) is true as premature redemption is permitted after the fifth year. Reason (R) is also true and correctly explains the rationale behind the provision, which balances liquidity with economic objectives.
Q3. Match the following columns related to the Sovereign Gold Bond Scheme:
Column I (Feature) | Column II (Description)
——————-|———————
A. Issue Date of SGB 2019-20 Series VI | 1. October 30, 2019
B. Premature Redemption Due Date | 2. October 30, 2026
C. Redemption Price Basis | 3. Simple average of closing price of gold for 3 business days
D. Price Publishing Authority | 4. India Bullion and Jewellers Association Ltd (IBJA)
Options:
A. A-1, B-2, C-3, D-4
B. A-2, B-1, C-4, D-3
C. A-1, B-2, C-4, D-3
D. A-3, B-1, C-2, D-4
Answer: ? — The correct matching is: A-1 (Issue Date: October 30, 2019), B-2 (Premature Redemption Due Date: October 30, 2026), C-3 (Redemption Price Basis: Simple average of closing price of gold for 3 business days), D-4 (Price Publishing Authority: India Bullion and Jewellers Association Ltd).
Mains Practice Question
✍ The Sovereign Gold Bond Scheme represents a strategic effort by the Government of India to monetise household gold holdings while providing an alternative investment avenue to investors. Critically examine the objectives, operational framework, and economic implications of the SGB Scheme. Also, analyse the significance of the redemption price determination mechanism in ensuring investor confidence and market stability. (15 Marks)
Approach: MODEL-ANSWER SKELETON:
1. **Objectives of SGB Scheme**:
– Monetisation of household gold holdings (reference to NITI Aayog and RBI reports on gold reserves).
– Reduction in import dependency for gold (data on gold imports and trade deficit).
– Providing a sovereign-backed, interest-bearing alternative to physical gold.
– Promoting financial inclusion by offering accessible investment options.
2. **Operational Framework**:
– Issuance mechanism: Government of India (GoI) and RBI through designated banks and financial institutions.
– Eligibility and subscription process (individuals, HUFs, trusts, etc.).
– Interest rate mechanism (fixed or floating; cite RBI notifications).
– Premature redemption provisions (post-fifth year; cite GOI notification F.No. 4(7)-B(W&M)/2019).
– Redemption price determination: Simple average of closing price of gold (999 purity) over three business days, published by IBJA (reference to RBI press release and IBJA role).
3. **Economic Implications**:
– **Positive**: Reduction in current account deficit (CAD) due to lower gold imports; formalisation of gold economy; revenue generation for the government via interest payments.
– **Challenges**: Market volatility and gold price fluctuations affecting redemption prices; liquidity constraints for investors; potential crowding out of other investment avenues.
4. **Redemption Price Mechanism**:
– **Significance**: Ensures transparency and market-linked pricing; protects investor interests by basing redemption on objective benchmarks.
– **Stability**: Reduces arbitrage opportunities and speculative trading; aligns with global best practices in commodity-linked securities.
– **Critique**: Dependence on IBJA’s gold price benchmark; potential delays in price publication affecting investor decisions.
5. **Conclusion**:
– Balance between sovereign backing and market dynamics.
– Need for periodic reviews of redemption mechanisms to align with global standards.
– Role of SGB in India’s broader strategy for gold monetisation and financial inclusion.
Source: RBI
Generated by AanyaAi for educational purpose.
Related guides on our sites
- Best PSIR optional coaching for upsc
- UPSC EPFO Test series
- Best PSIR optional test series
- Best PSIR optional teacher for upsc

- SGB 2019-20 Series VI: Redemption Price for Premature Redemption on Oct 30, 2026 - October 30, 2026
- Kerala HC seeks state response on witness protection scheme delay - October 30, 2026
- केरल के कासरगोड में पारंपरिक सुरंगम पुनर्जीवित करने की पहल, जानिए कैसे होगा लाभ - October 30, 2026
No Comments